On 15 October 2025, Germany’s Federal Ministry of Finance (BMF) published guidance relevant to every business that receives or sends electronic invoices.
For the first time, it clearly distinguishes between format errors, business rule errors and content errors, and explains what each means for the validity of an invoice.
Many businesses are now asking:
When must an e-invoice be rejected?
When may it be accepted?
And what happens if a file is technically valid but its content is incorrect?
This article summarises the BMF guidance in plain language and uses examples to explain what to look out for.
1. Checking an e-invoice in several stages
The BMF distinguishes three levels of checking:
- Format validation — is the file technically well structured and does it comply with the business rules of European standard EN 16931?
- Content checks for statutory correctness — are the mandatory details required by the German VAT Act (§§ 14 and 14a UStG) correct?
- Other content checks — does the invoice comply with the selected format, such as XRechnung or ZUGFeRD, and is it arithmetically and factually correct?
Does it actually charge for the services provided or goods delivered, and has the correct tax treatment been applied?
An e-invoice is completely free of errors only when it meets all three levels.
2. Format errors — the basic technical case
A format error occurs when a file does not meet EN 16931 requirements or is not machine-readable.
In this case it is not an e-invoice, but an “other invoice in a different electronic format”.
Example: missing currency
Example: EN 16931 requires the currency to be specified. If it is missing from the XML file, this is a format error, even if UBL or CII does not generate a technical error message.
BR-5: An invoice must have an invoice currency code (BT-5).
EN16931-1:2017
Neither CrossIndustryInvoice nor UBL technically requires the currency field:
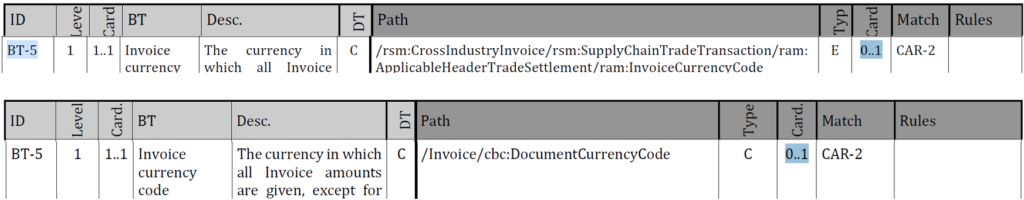
This example shows that European standard EN 16931 clearly requires the invoice currency (BT-5). Cardinality 1..1 means the field must appear exactly once.
In the underlying CII and UBL syntaxes, however, the field has cardinality 0..1 and is therefore technically optional.
An XML file can therefore be formally valid without a currency, while failing to meet the business requirements of EN 16931.
In practice, this results in a format error because the invoice is not fully compliant with the standard, even if its technical structure is correct.

The result: this is not an e-invoice but an other electronic invoice, which may only be accepted with the recipient’s consent.
Consequence: during the transitional period, before mandatory sending applies, the recipient may accept such an invoice but does not have to.
Once the issuer is required to issue an e-invoice, the recipient must reject invoices with format errors.
3. Business rule errors — linking technology and content
European standard EN 16931 and formats based on it, including XRechnung and ZUGFeRD, define business rules.
These rules describe which information an e-invoice must contain and how the information is logically related.
For example:
If an invoice states a tax rate, it must also state the corresponding tax amount.
Similarly, if a discount amount is specified, its reason must not be missing.
Many of these business rules can be checked technically. This is precisely what validation tools do: automatically check these relationships.
Other rules, such as economic plausibility or tax interpretation, must be checked manually or with the help of an ERP system.
Business rules support both levels
Business rules play a part in two phases of checking:
- During format validation
They ensure the file is technically correct and compliant with EN 16931.
An error found here is a format error.
→ Example: a mandatory detail required by the standard is missing or in the wrong place. - During content checks
They help establish whether the invoice is consistent and complete: whether its details fit together logically and meet VAT requirements.
→ Example: the seller’s address is incomplete. EN 16931 itself requires only the name and country.
The four validation stages at a glance
Technical and content validation build on each other step by step:
- Technical validation — CII/UBL structure (XSD)
- EN 16931 business rule validation — European core rules
- CIUS / extension business rule validation — national or industry-specific additions, such as XRechnung and ZUGFeRD
- Content checks — ERP system or manual

Technical CII/UBL validation under EN 16931 proceeds through business rule checks before the final content review.
4. Content errors — factual, arithmetic or tax errors
Content errors concern the actual substance of the invoice.
They arise when an invoice is incorrect in its tax treatment, arithmetic or facts, for example through incorrect amounts, tax rates or service descriptions.
However, not every content error automatically makes an invoice non-compliant within the meaning of the German VAT Act.
An invoice is non-compliant under § 14 UStG only when
the statutory mandatory details under §§ 14 and 14a UStG are incomplete or incorrect.
Content that can be checked technically or substantively
- Content that can be checked technically
Some content errors can be identified using business rules checked automatically by validation tools.
Examples include:- Inconsistencies between tax rate and tax amount
- Missing mandatory fields, such as the invoice date or recipient address
- Invalid code-list values, such as currencies, countries or units of measure
- Content requiring substantive or manual checks
Other content cannot be checked automatically and requires assessment by the ERP system or a manual review.
Examples include:- Whether the invoiced service was actually provided
- Whether the correct tax treatment was selected
- Whether amounts are arithmetically correct
Validation tools document technically verifiable content in a validation report.
Examples of content errors
- Incorrect or missing tax amount
- Incorrect tax rate or tax exemption
- Incomplete service description
- Incorrect issue date
- Incorrect or missing tax number / VAT identification number
- Incorrect quantities, prices or totals
How to distinguish them
- Content error = the invoice is incorrect in its tax treatment, arithmetic or facts
- Non-compliant invoice (§ 14 UStG) = mandatory details are incomplete or incorrect
This means:
An invoice may contain content errors yet remain correct for VAT purposes, for example if a price is wrong but all mandatory details are present and correct.
Conversely, a missing mandatory detail, such as the seller’s VAT identification number or tax number, is always a defect relevant to VAT.